Chapter 6 - The Meeting Behind Closed Doors
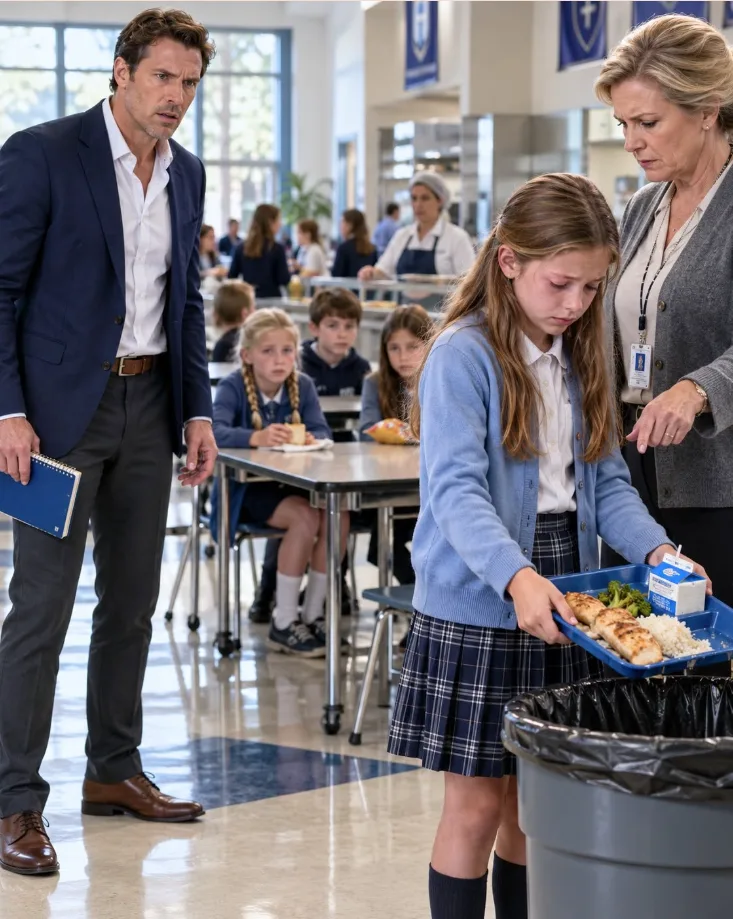
Thomas Caldwell had served on Hawthorne Academy's board for nine years.
He was a successful real estate developer, a generous donor, and a familiar face at charity galas throughout North Carolina.
Parents trusted him.
Teachers respected him.
And until that week, I had considered him a reliable partner in the school's charitable work.
When Rebecca presented the email, Thomas denied any wrongdoing.
“The transfer was an accounting adjustment,” he said during an emergency board session. “No money was stolen. The school was consolidating restricted funds into a central account to improve efficiency.”
“Then why were the transfers concealed from the foundation?” Rebecca asked.
“They weren't concealed.”
“Your email explicitly asks whether the foundation will request individual transaction records.”
Thomas adjusted his tie.
“That was a question about administrative burden.”
Margaret stared at him.
“Thomas, did you know children were being denied meals?”
“Of course not.”
“Did you know Mrs. Harper's company was receiving payments?”
“I knew she provided consulting services.”
“Did you verify those services?”
He hesitated.
“I trusted the administration.”
It was the first answer that sounded honest.
Unfortunately, trust was not an accounting method.
The independent auditors eventually obtained the original bank statements. They traced the questionable transfers to three separate accounts.
One belonged to Harper Educational Services.
Another belonged to a general school operating account.
The third was controlled by a nonprofit organization Thomas had helped establish.
That organization was legally separate from Hawthorne Academy, but it shared office space with one of his development companies.
The auditors found that money from the Angel Account had been transferred into the nonprofit before being used to pay several unrelated expenses.
Some payments appeared to cover legitimate school activities.
Others lacked adequate documentation.
And a portion of the funds had been spent on a fundraising reception attended by prominent donors.
The event had featured catered dinners, floral arrangements, and an expensive audiovisual package.
Its promotional materials claimed that the evening would “celebrate the power of feeding every child.”
Meanwhile, children at Hawthorne had been told there was no money for their lunches.
When the findings became public, Thomas resigned from the board.
Whitaker was placed on administrative leave.
Mrs. Harper's consulting company stopped receiving payments.
But the investigation had not yet established whether the transfers were criminal, negligent, or the result of multiple failures in financial oversight.
That determination would take time.
For the families, however, the immediate problem remained painfully simple.
They needed food.
The school board authorized emergency meal funding from its operating budget while the disputed money was traced. Local businesses donated groceries, and several parents volunteered to help distribute meals.
My foundation offered temporary support, but I insisted on a written agreement requiring independent oversight.
I would not allow the program to depend on anyone's personal assurances again.
Then something unexpected happened.
A woman named Denise Parker contacted Rebecca.
Denise had worked in Hawthorne's finance office for seven years before resigning the previous spring. She had heard about the investigation and wanted to provide information.
We met her at Rebecca's office.
Denise brought a small box of printed emails and handwritten notes.
“I tried to raise concerns last year,” she explained. “At first, I thought the discrepancies were mistakes. Then I noticed that applications were being marked incomplete even when families had submitted every required document.”
“Who was making those decisions?” Rebecca asked.
“Mrs. Harper handled eligibility. Principal Whitaker approved the program budgets. Mr. Caldwell attended the quarterly meetings.”
“Did you tell them what you found?”
“I did.”
Denise opened the box.
One of her notes described a meeting in which she had questioned why meal assistance funds were being transferred to unrelated accounts.
According to her notes, Whitaker told her that the school needed flexibility to cover unexpected expenses.
Thomas had reportedly added that donors cared about outcomes, not the details of internal accounting.
Denise had asked for written authorization.
Instead, she was told to stop creating unnecessary obstacles.
A month later, her position was eliminated during a departmental restructuring.
“Were you fired for raising concerns?” Rebecca asked.
“I can't prove that,” Denise replied. “But I can prove that I raised them.”
She handed over the emails.
One message from Whitaker to Thomas contained a particularly troubling line.
We need to make sure the donor sees the reports before the families start asking questions.
The date was three weeks before I received the first quarterly report.
Rebecca looked at me.
“They weren't simply making mistakes. At least some people knew the reports did not tell the full story.”
I stared at the page.
For months, I had believed my donation was helping children.
Now I wondered how many people had looked at those children and seen only an inconvenient expense.
That night, Claire came into my bedroom carrying her drawing journal.
“Dad?”
I put aside my laptop.
“What is it, sweetheart?”
She sat beside me.
“Will the kids get lunch tomorrow?”
I took her hand.
“Yes.”
“All of them?”
I thought about the auditors, the legal proceedings, the board meetings, and the money that might never be recovered.
Then I looked into my daughter's eyes.
“We're going to do everything we can to make sure of it.”
She nodded.
After a moment, she opened her journal to a new page.
At the top, she had written:
Things That Should Never Happen at School.
The first item read:
May you like
No child should have to be brave just to eat.
I hoped that, one day, it would no longer need to be written.