Chapter 3 - The Account Richard Tried to Hide
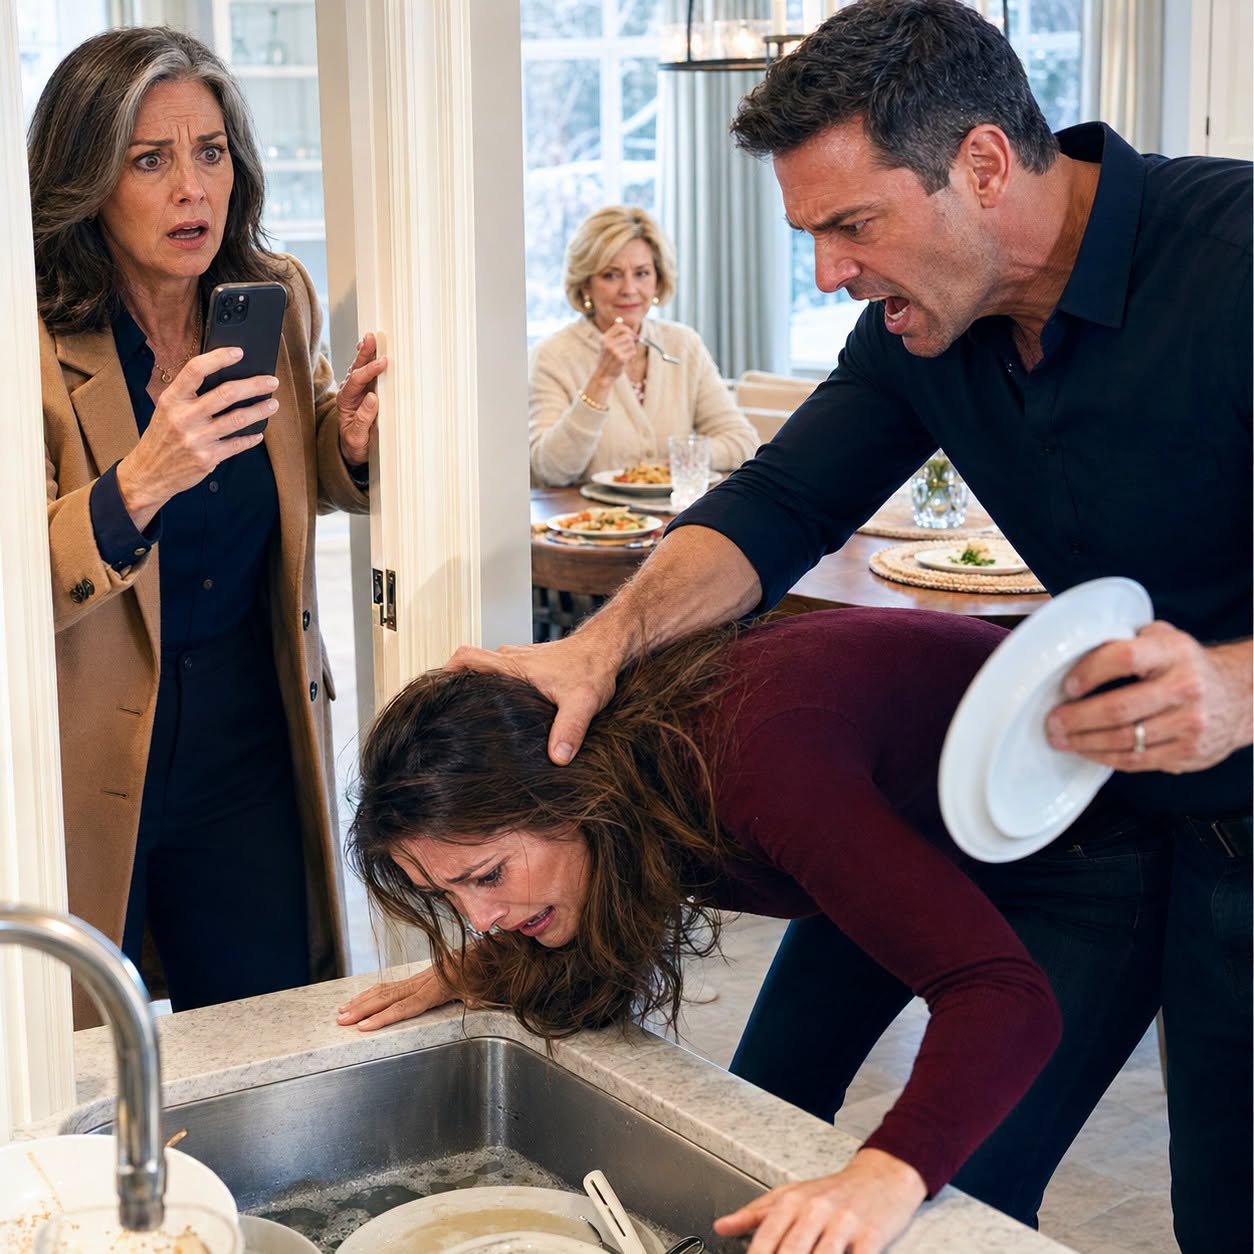
By nine o’clock that evening, my daughter was sitting at my kitchen table wearing one of my old sweaters, a blanket wrapped around her shoulders, and an expression I had never seen on her face before.
She looked like someone who had escaped a burning building only to discover that the fire was following her.
I had called a domestic violence support service and spoken with an advocate named Karen, who helped us develop a safety plan. She advised us to preserve the threatening messages, avoid confronting Richard alone, and contact an attorney experienced in financial abuse. We also agreed that Emily should have her injuries documented by a medical professional.
For the first time all day, I felt we were taking practical steps instead of simply reacting to fear.
But the photographs and bank statements remained spread across my kitchen table.
And the number 4419 kept appearing in my thoughts.
“Do you recognize that account number?” I asked.
Emily shook her head.
“I've never seen it before. Richard kept most of his business documents in a locked cabinet in his office. Whenever I asked about them, he said they were confidential.”
“Did you ever see him receive mail from Whitmore Consulting Group?”
She thought for a moment.
“Once. A large envelope arrived about six months ago. He took it upstairs before I could read the label.”
“Did he say what it was?”
“He told me it was a tax document.”
I leaned back in my chair.
Richard had always presented himself as a successful financial consultant. When Emily first introduced him to me, he had arrived at my house wearing an expensive watch and speaking confidently about investment portfolios, property acquisitions, and the importance of protecting family wealth.
I had admired his ambition.
Now I wondered how much of that polished image had been carefully constructed to deceive us.
“There's something else,” Emily said.
She reached into her bag and removed a small notebook with a cracked leather cover.
“I started writing things down after the money disappeared.”
Inside were dates, amounts, and brief descriptions of arguments. Some entries mentioned missing bank statements. Others described Richard demanding that she sign documents she hadn't been allowed to read.
One entry stopped me cold.
October 3. Patricia said I should be grateful Richard married me. She said my inheritance would have disappeared eventually anyway. Richard told her to stop talking because I wasn't supposed to know about the second account.
I read the sentence twice.
“The second account,” I murmured.
Emily nodded.
“That was the first time I heard them mention it. I was coming downstairs when I heard them talking in the dining room. They didn't know I was there.”
“What did they say?”
“Patricia asked whether the transfers were complete. Richard told her there was still one payment to arrange. Then he said something about a signature.”
“What signature?”
“I don't know. When they heard me moving, they stopped talking.”
I looked at the notebook again.
“Emily, did you sign any documents when you got married?”
“Of course. The marriage license, insurance forms, and some financial paperwork Richard said we needed for our mortgage.”
“Did you read everything?”
Her face fell.
“No.”
She spoke so quietly that I almost missed the answer.
“I trusted him.”
I reached across the table and covered her hand.
“Trusting your husband wasn't a crime, sweetheart.”
She stared at our joined hands.
“It feels like I handed him a weapon.”
“No. He chose to misuse your trust. That's his responsibility, not yours.”
For a moment, she looked as though she might cry again.
Then my phone rang.
The caller was an unfamiliar number.
I let it go to voicemail.
Seconds later, a message appeared.
This is Daniel Brooks, an attorney representing Richard Hayes. My client is concerned about his wife's sudden departure and would appreciate an opportunity to discuss a peaceful resolution.
I showed Emily.
Her expression changed instantly.
“He already has a lawyer?”
“He may have had one for some time.”
She stood so quickly that the chair scraped against the floor.
“Mom, we need to leave.”
“Why?”
“Because Richard always gets ahead of everything. If his lawyer is contacting you already, he knows we're looking into the money.”
I tried to remain calm.
“An attorney contacting us doesn't mean Richard knows everything we've discovered.”
“You don't understand him.”
“Then help me understand.”
She pressed both hands against her temples.
“Richard never panics. He plans. When something goes wrong, he already has an explanation ready. He'll make me look unstable. He'll say I stole money, that I abandoned him, that I'm having some kind of breakdown.”
I remembered the way Patricia had filmed Emily at the sink.
The way Richard had called her emotional.
The way both of them had seemed prepared to turn cruelty into evidence against its victim.
“Then we make sure we have our own evidence,” I said.
I called Karen again and asked for guidance about finding an attorney. She gave us several practical recommendations and reminded us not to access any account or device that didn't belong to us.
We agreed that Emily would change passwords for her personal email and accounts from a safe device, contact her bank directly, and ask whether any transactions could be investigated or challenged.
We did not try to access Richard's private accounts.
We didn't need to.
The next morning, Emily contacted her bank.
After answering security questions and verifying her identity, she requested copies of the account records and reported transactions she did not recognize.
The representative confirmed that several transfers had originated from Emily's personal account. Some appeared to have been authorized electronically. Others required additional investigation.
Then the representative asked a question that made Emily go silent.
“Mrs. Hayes, did you knowingly authorize the opening of a joint credit facility secured against your inheritance account?”
Emily looked at me.
“What joint credit facility?”
The representative explained that the bank's records showed an application associated with her name and Richard's.
Emily had never knowingly agreed to it.
The application listed an available credit limit of $250,000.
A large portion had already been drawn.
When the call ended, Emily sat motionless.
“He borrowed against my money,” she whispered.
I felt a wave of anger, but I forced myself to breathe.
“We'll let the bank investigate. We won't jump to conclusions until we see the documents.”
Emily opened the notebook again.
“Mom, I think I know where the papers are.”
She explained that Richard had recently moved several boxes from his office into a rented storage unit. He had told Patricia that the boxes contained old business files.
Emily had seen the address on a receipt left beside the telephone.
She remembered it because Richard had become unusually angry when she picked up the paper to move it.
We gave the information to her attorney, who advised us to preserve what we had and avoid entering any property without permission.
That afternoon, the attorney called back.
He had reviewed the initial bank documents and noticed something unusual.
The company receiving the transfers was registered to a business address in Delaware. Its listed manager was a woman named Patricia Hayes.
Richard's mother.
But the most disturbing discovery involved a document attached to the credit application.
It carried Emily's electronic signature.
She stared at the screen when the attorney showed us a copy.
“That isn't how I sign my name,” she said.
I leaned closer.
The signature looked similar to hers, but the final letter was wrong. Emily had always signed her name with a distinctive upward stroke.
This signature ended in a sharp downward line.
“Could someone have copied it?” I asked.
“Possibly,” the attorney replied. “But we need the bank's authentication records and the original application before drawing conclusions. A signature discrepancy alone doesn't establish fraud.”
Emily nodded slowly.
Then she pointed to a paragraph near the bottom of the document.
“What's that?”
The attorney enlarged the text.
It was a clause authorizing the transfer of certain funds if the borrower defaulted.
The collateral included the account into which Emily's inheritance had been deposited.
And the person listed as the secondary guarantor was Patricia Hayes.
Emily covered her mouth.
“My mother-in-law signed for a loan using my inheritance?”
“We don't know exactly what happened yet,” the attorney said carefully. “But the records raise serious questions.”
I looked at my daughter.
Her eyes were wet, but something new had appeared in them.
Not just fear.
Anger.
For months, Richard had convinced her that she was confused, irresponsible, and incapable of understanding money.
Now the documents suggested that she had been asking the right questions all along.
That evening, another message arrived from Richard's attorney.
My client requests that Mrs. Hayes return to the marital residence by tomorrow morning to discuss her obligations. Continued refusal may affect future proceedings.
Our attorney replied that all further communication should go through him.
For the first time since leaving Richard's house, Emily slept for several hours without waking in panic.
I sat beside her bedroom door until I heard her breathing settle.
Then I returned to the kitchen and looked at the bank documents again.
The transfers were troubling.
The disputed signature was troubling.
But one question bothered me more than everything else.
Why had Patricia told Richard not to let Emily leave because their family's work might fall apart?
What had the two of them been building together?
And why had they needed Emily's money to do it?
At 6:17 the following morning, my phone rang.
It was Emily's attorney.
“Margaret,” he said, his voice unusually serious, “we've found a second company connected to the transfers. Its records contain a name you should know.”
I sat upright.
“Whose name?”
“Your daughter's.”
I felt the room go cold.
“How?”
“Her name appears as a director, and there's a document dated eight months ago that appears to authorize the company to make financial decisions on her behalf.”
I looked toward the staircase.
Emily was still asleep.
“Did she sign it?”
“That's what we need to establish.”
He paused.
“But there's another problem. The company has outstanding obligations that may exceed half a million dollars.”
I gripped the telephone.
“Are you saying my daughter owes that money?”
“I'm saying someone has placed her name in a position that could expose her to serious financial and legal consequences. We need to determine whether the documents are genuine, whether she understood what she was signing, and whether any laws were broken.”
I looked at the folded bank statement lying on the table.
Richard had not simply taken money from my daughter.
He might have been preparing to leave her with the debts, the consequences, and the blame.
May you like
And if that was true, then the bruise on her wrist was only one part of a much larger nightmare.
End of Chapter 3