Chapter 7 - The Truth in the Boardroom
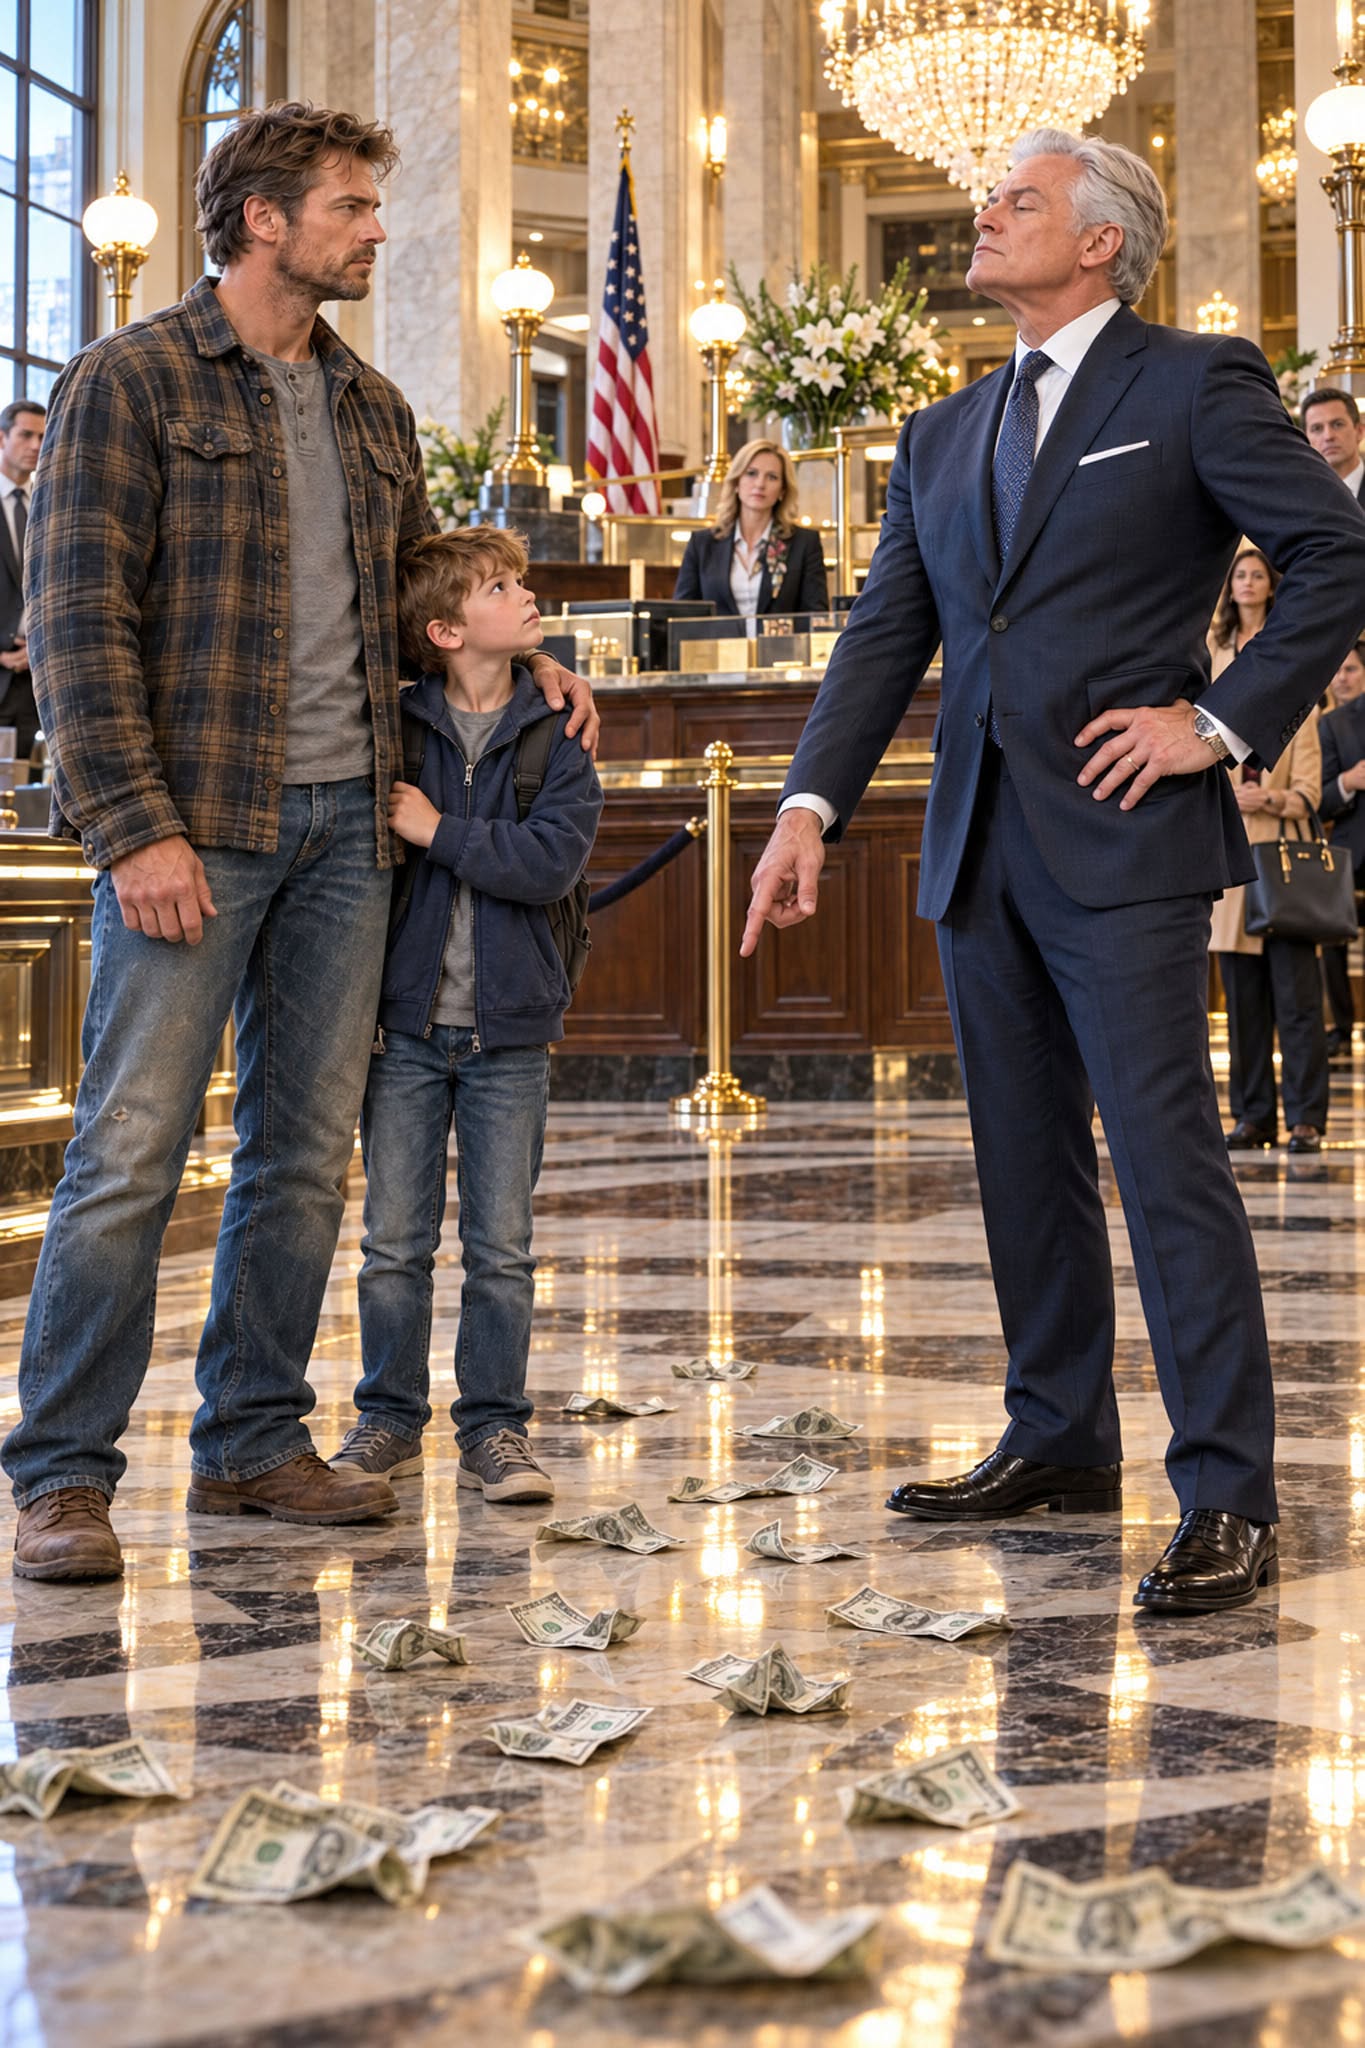
The emergency board meeting began at eight on Friday morning.
By then, the independent auditors had confirmed that the Meridian Ridge loans contained substantial valuation discrepancies. They had also identified transactions requiring further investigation.
The findings were serious, but they were not a final determination of fraud.
That distinction became important when Everett entered the room carrying a thick binder.
“I've prepared a response to the allegations,” he announced.
He distributed copies to the directors.
His argument was straightforward: the real-estate market had changed, the valuations reflected legitimate business judgments, and the bank's financial difficulties were being exaggerated by an investor attempting to gain influence.
Then he turned toward me.
“Mr. Calloway has a financial incentive to make Sterling Valley appear weaker than it is. If the proposed investment collapses, he may benefit from purchasing distressed assets at a discount.”
It was a clever accusation.
It was also incomplete.
I placed my own documents on the table.
“Northstar has no agreement to purchase the bank's distressed assets. Our proposed recapitalization is contingent on independent due diligence. If the bank cannot demonstrate reliable financial reporting, we won't invest. That's a risk-control decision, not an attempt to manufacture losses.”
One director nodded.
Everett pressed on.
“And what about the supposed connection between Meridian Ridge and my family? My nephew has many business interests. I cannot be responsible for every transaction involving people I know.”
“Agreed,” I said.
He seemed surprised.
“Personal relationships alone don't establish wrongdoing. That's why we have requested a review of the actual transactions, approvals, disclosures, and beneficial ownership records.”
Margaret distributed the auditor's preliminary report.
It showed that the concerns Daniel Reeves had raised fourteen months earlier were consistent with the discrepancies now identified.
The report also established that certain loan accounts had been temporarily adjusted around reporting dates without adequate supporting documentation.
Everett read silently.
Then he pushed the report away.
“An accounting irregularity is not proof of misconduct.”
“No one has said otherwise,” Margaret replied. “But the board has a responsibility to investigate.”
Everett turned toward her.
“You were my CFO. You signed the quarterly reports.”
The room became still.
Margaret's face tightened.
“Yes,” she said. “I did. I relied on the records provided by the lending department and the certifications supplied by senior management. When discrepancies emerged, I initiated an independent review.”
“Convenient.”
She took a breath.
“I should have demanded additional verification earlier. I accept responsibility for not identifying the problems sooner. But that doesn't excuse anyone who may have knowingly concealed them.”
Her voice trembled slightly, yet she continued.
“I am prepared to cooperate fully with the investigation, including a review of my own decisions.”
For the first time, I saw the board members truly listen to her.
She wasn't trying to present herself as perfect. She was acknowledging what she had done wrong while refusing to conceal what others might have done.
Everett had no answer.
Then the board's independent chair, Eleanor Brooks, spoke.
“We have reviewed the preliminary evidence and the advice of outside counsel. Until the investigation is complete, we propose restricting Mr. Sloan's authority over related-party lending, suspending his access to the archive system, and appointing an independent executive committee to oversee the bank's operations.”
Everett stood so quickly that his chair rolled backward.
“You cannot remove my authority!”
“Your authority comes from the board,” Eleanor said. “And the board has a duty to protect the institution.”
“This is a coup!”
“No,” she replied. “It's governance.”
The directors voted.
Five supported the restrictions.
Two opposed them.
Everett stared at the results as if he couldn't comprehend what he was seeing.
“You'll destroy everything I've built,” he said.
Eleanor remained composed.
“If the institution cannot survive an honest investigation, then we have a much bigger problem than anyone in this room wants to admit.”
Everett turned toward me.
“This is what you wanted.”
I looked directly at him.
“I wanted the bank to be honest. I wanted depositors protected. I wanted employees to stop being threatened for raising legitimate concerns. I wanted a nine-year-old boy to be treated like a human being.”
His expression twisted.
“You're using a child to make yourself look noble.”
“No. I'm reminding you that the people you dismiss are still people when nobody important is watching.”
For several seconds, the only sound was the hum of the ventilation system.
Then Everett gathered his binder.
“You'll regret this.”
He walked out.
Nobody followed him.
The meeting continued for another hour. The directors approved the independent investigation, agreed to preserve all relevant evidence, and authorized the development of a restructuring plan.
When it ended, Margaret approached me.
“I never thought I'd see the day he lost control of a meeting.”
“Neither did I.”
“Do you still intend to invest?”
“I intend to finish the review. The bank's employees and customers deserve a fair assessment.”
She looked toward the door Everett had used.
“Do you think he'll cooperate?”
I thought about his face when the directors voted.
“I think he'll do whatever he believes will save him.”
Unfortunately, that didn't mean he would do what was best for the bank.
And before the day was over, we learned just how determined he was to protect himself.
At 4:40 p.m., independent counsel received a notice that Everett had retained his own attorney and would no longer answer questions without legal representation.
That was his right.
But shortly afterward, a new message appeared in the bank's internal system.
It was addressed to the executive committee.
Effective immediately, I withdraw my support for the proposed recapitalization and will pursue all available options to protect my interests.
The message was signed by Everett Sloan.
And attached to it was a letter claiming that Northstar's proposed investment agreement had been improperly negotiated.
The dispute threatened to delay the rescue plan.
For the first time, I wondered whether the bank could be saved before its financial position deteriorated further.
Then Margaret called with an unexpected suggestion.
“Grant, what if we stop treating this as a negotiation between you and Everett?”
“What do you mean?”
“What if we put the employees, depositors, and independent directors at the center of the plan—and let the evidence determine what happens to the chairman?”
I looked at the notes on my desk.
For six weeks, we had been negotiating with Sterling Valley as though the bank were a collection of assets, liabilities, and executive decisions.
Perhaps it was time to remember what it had been created to do.
Help people build their lives.
“Prepare a proposal,” I said. “One that protects the bank first.”
May you like
For the first time in days, Margaret sounded hopeful.
“I'll start tonight.”